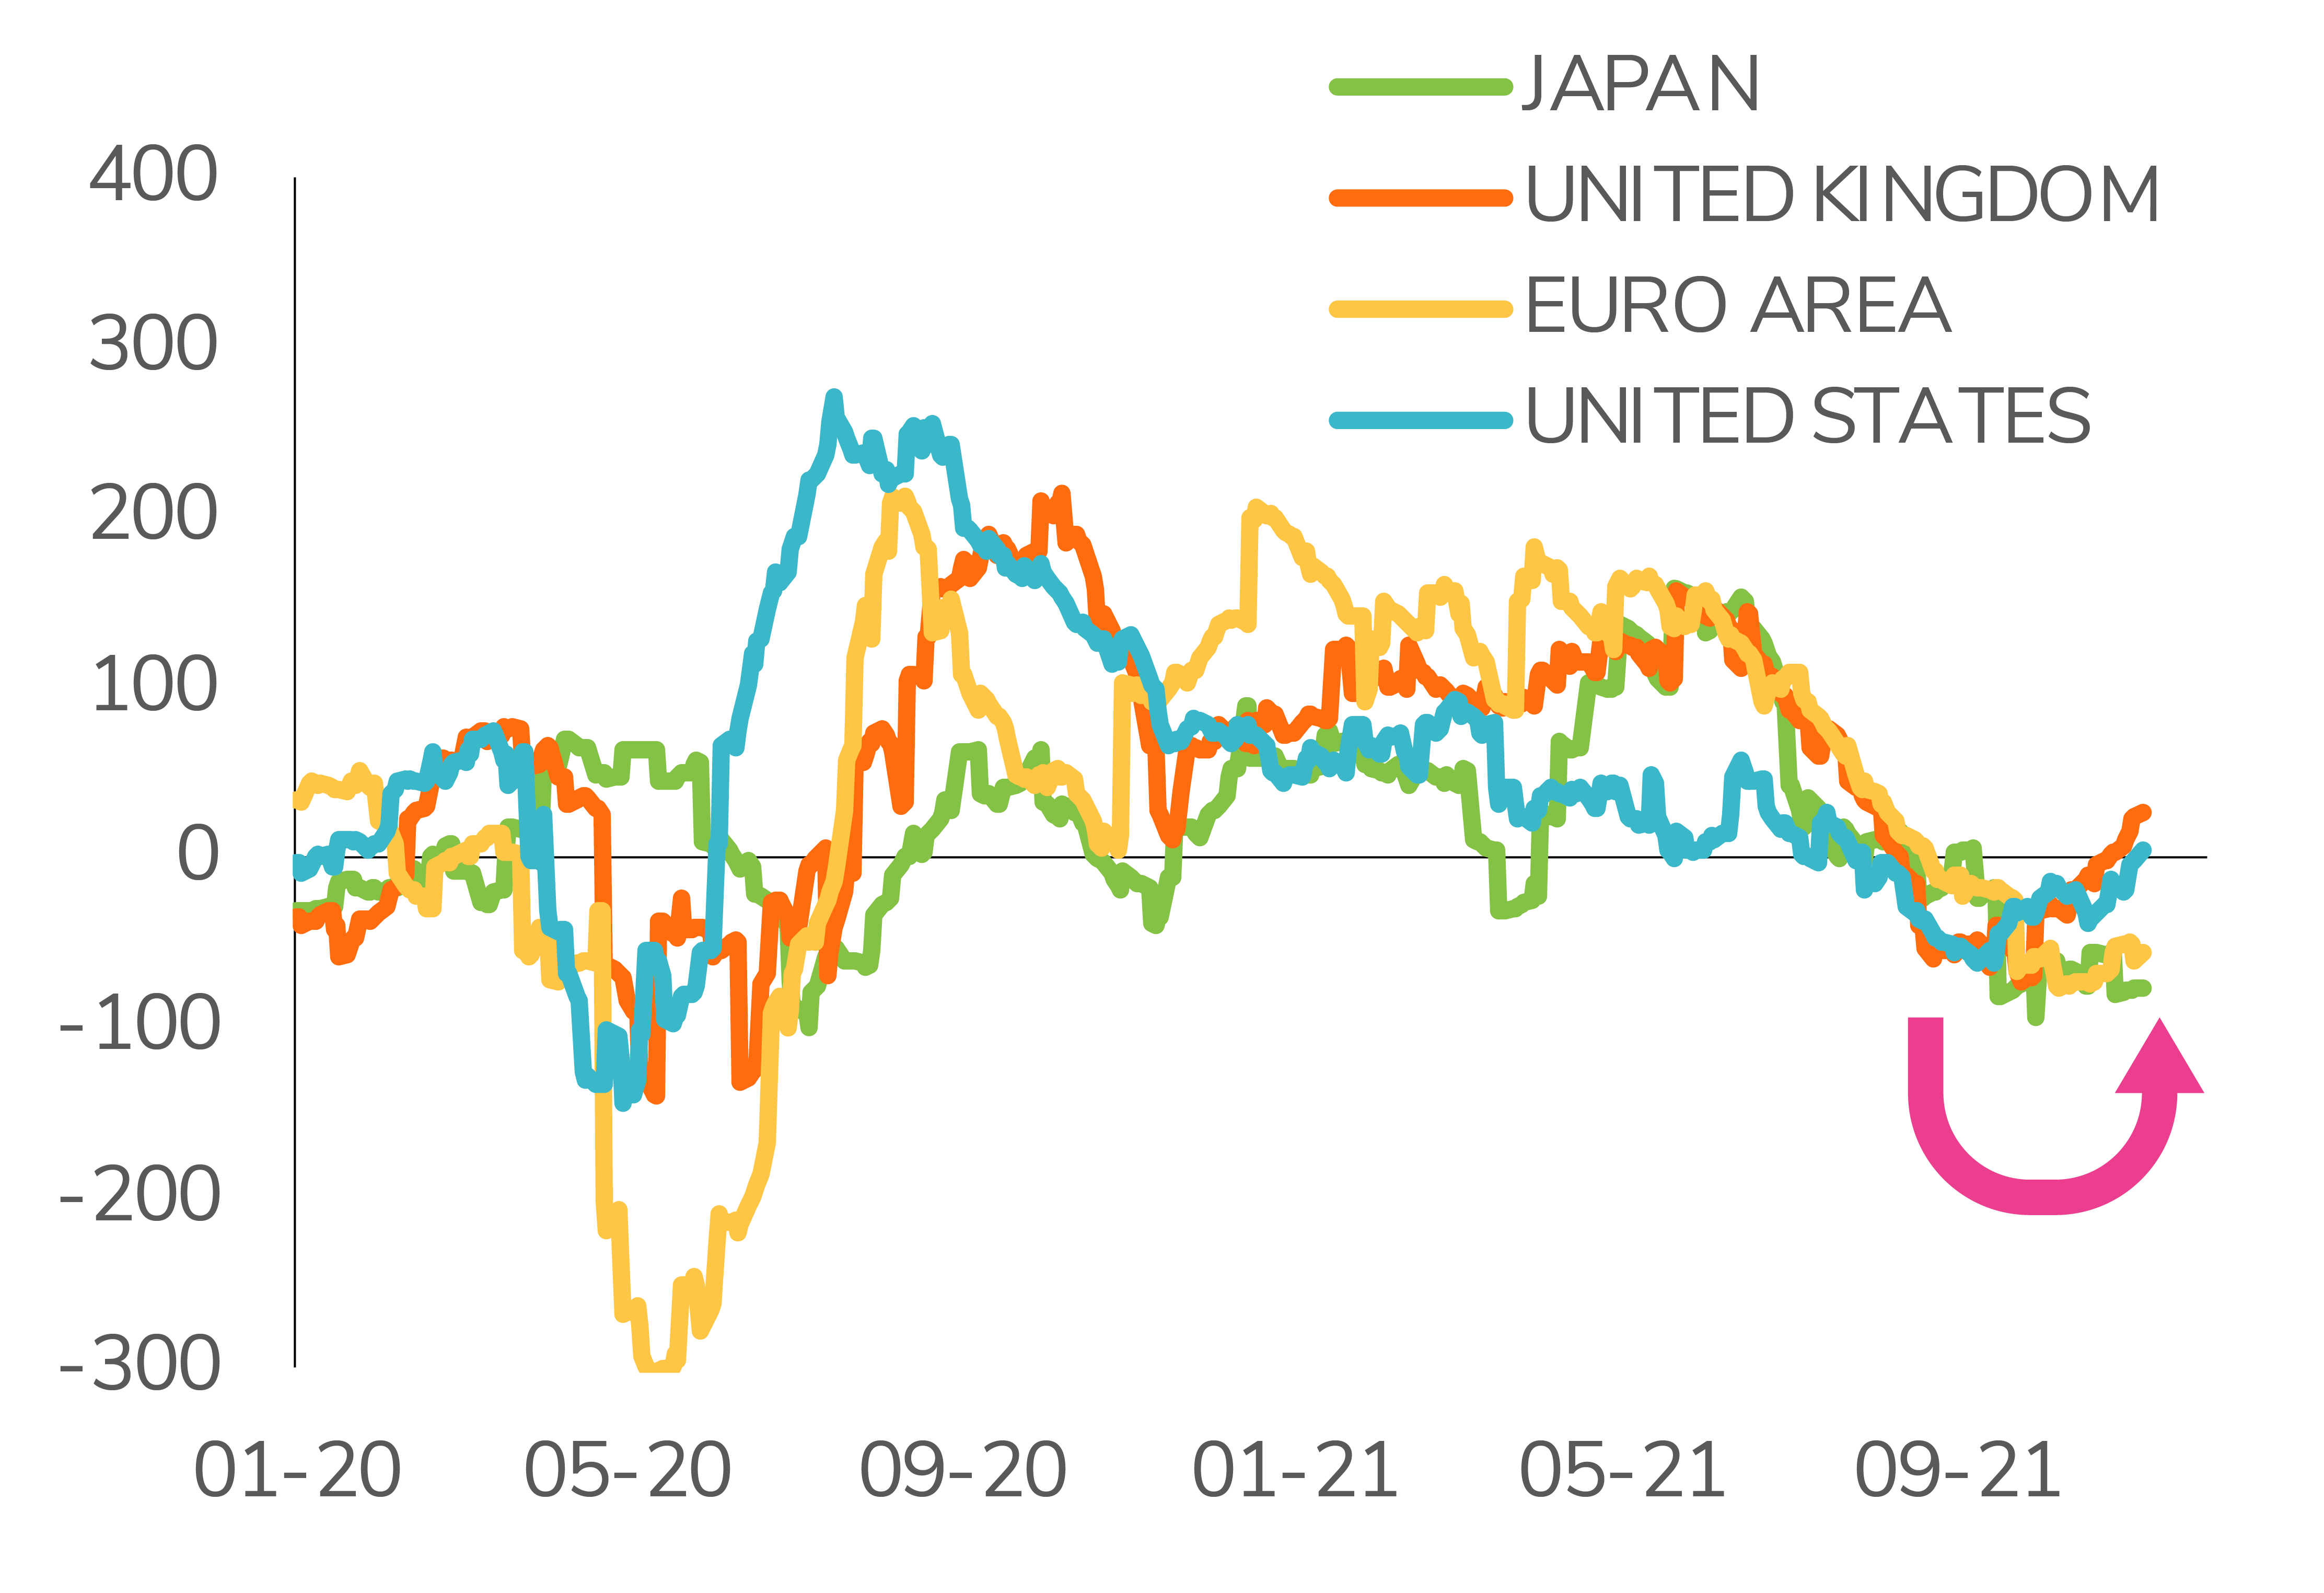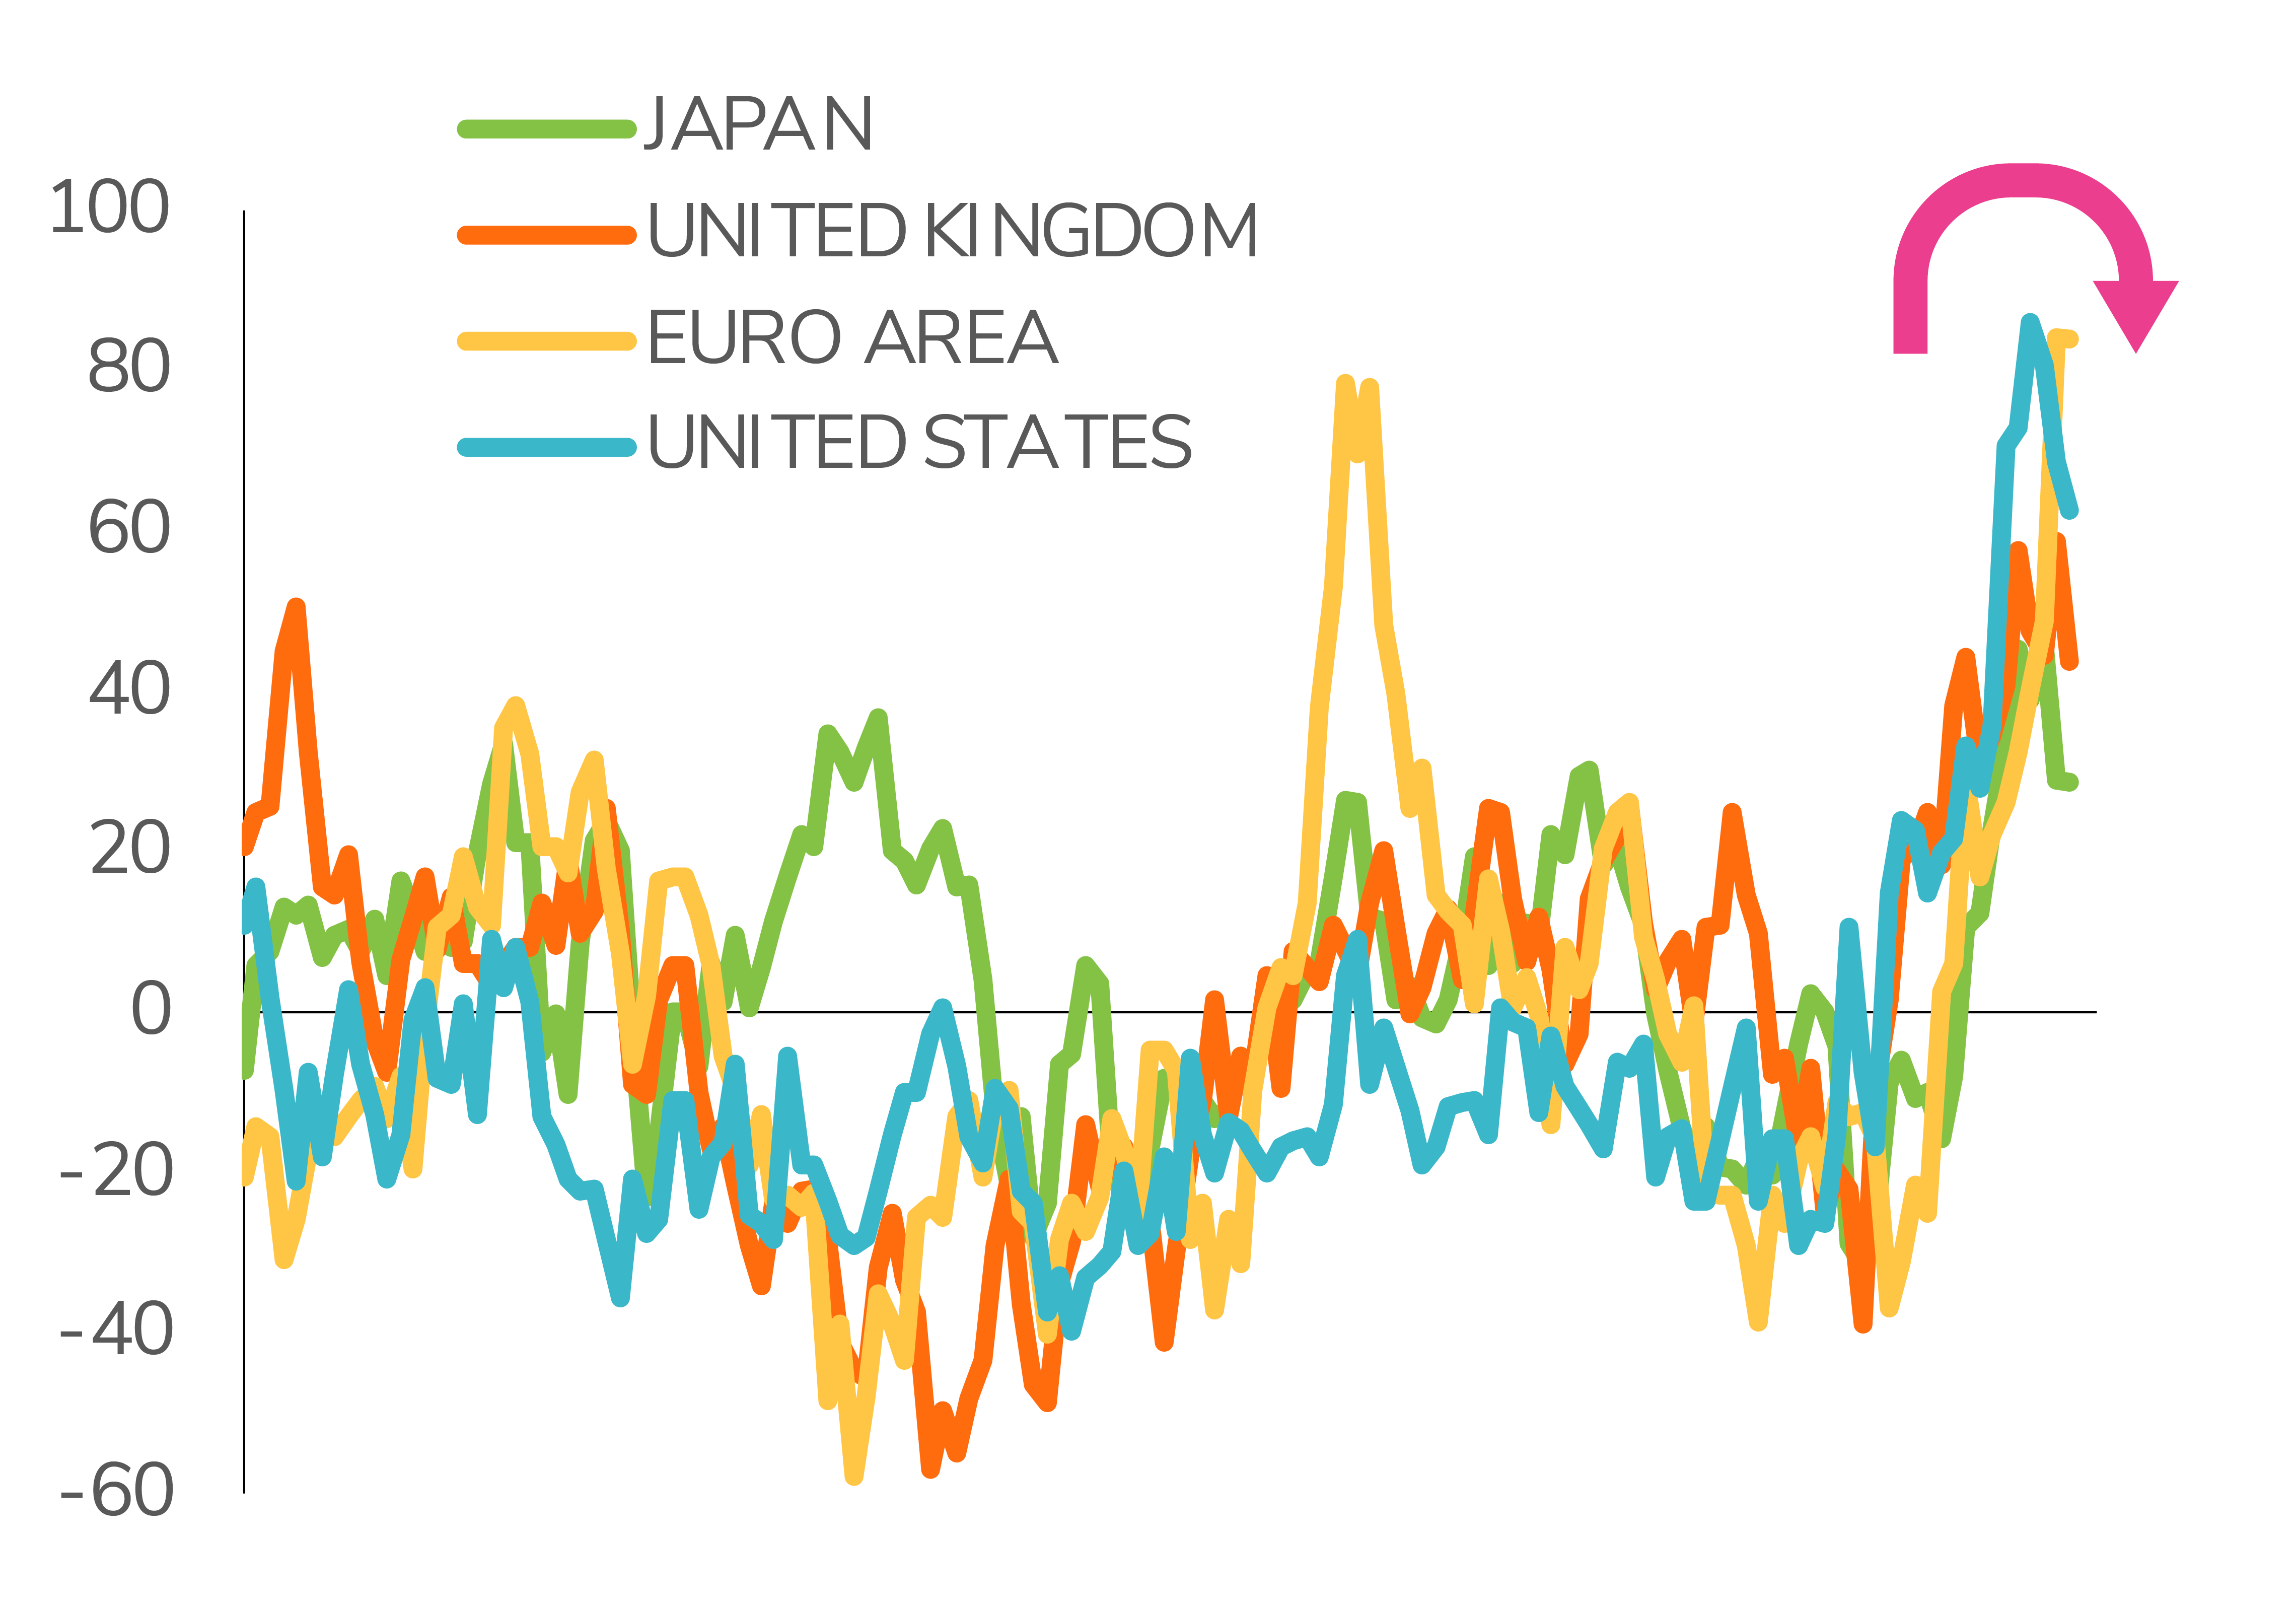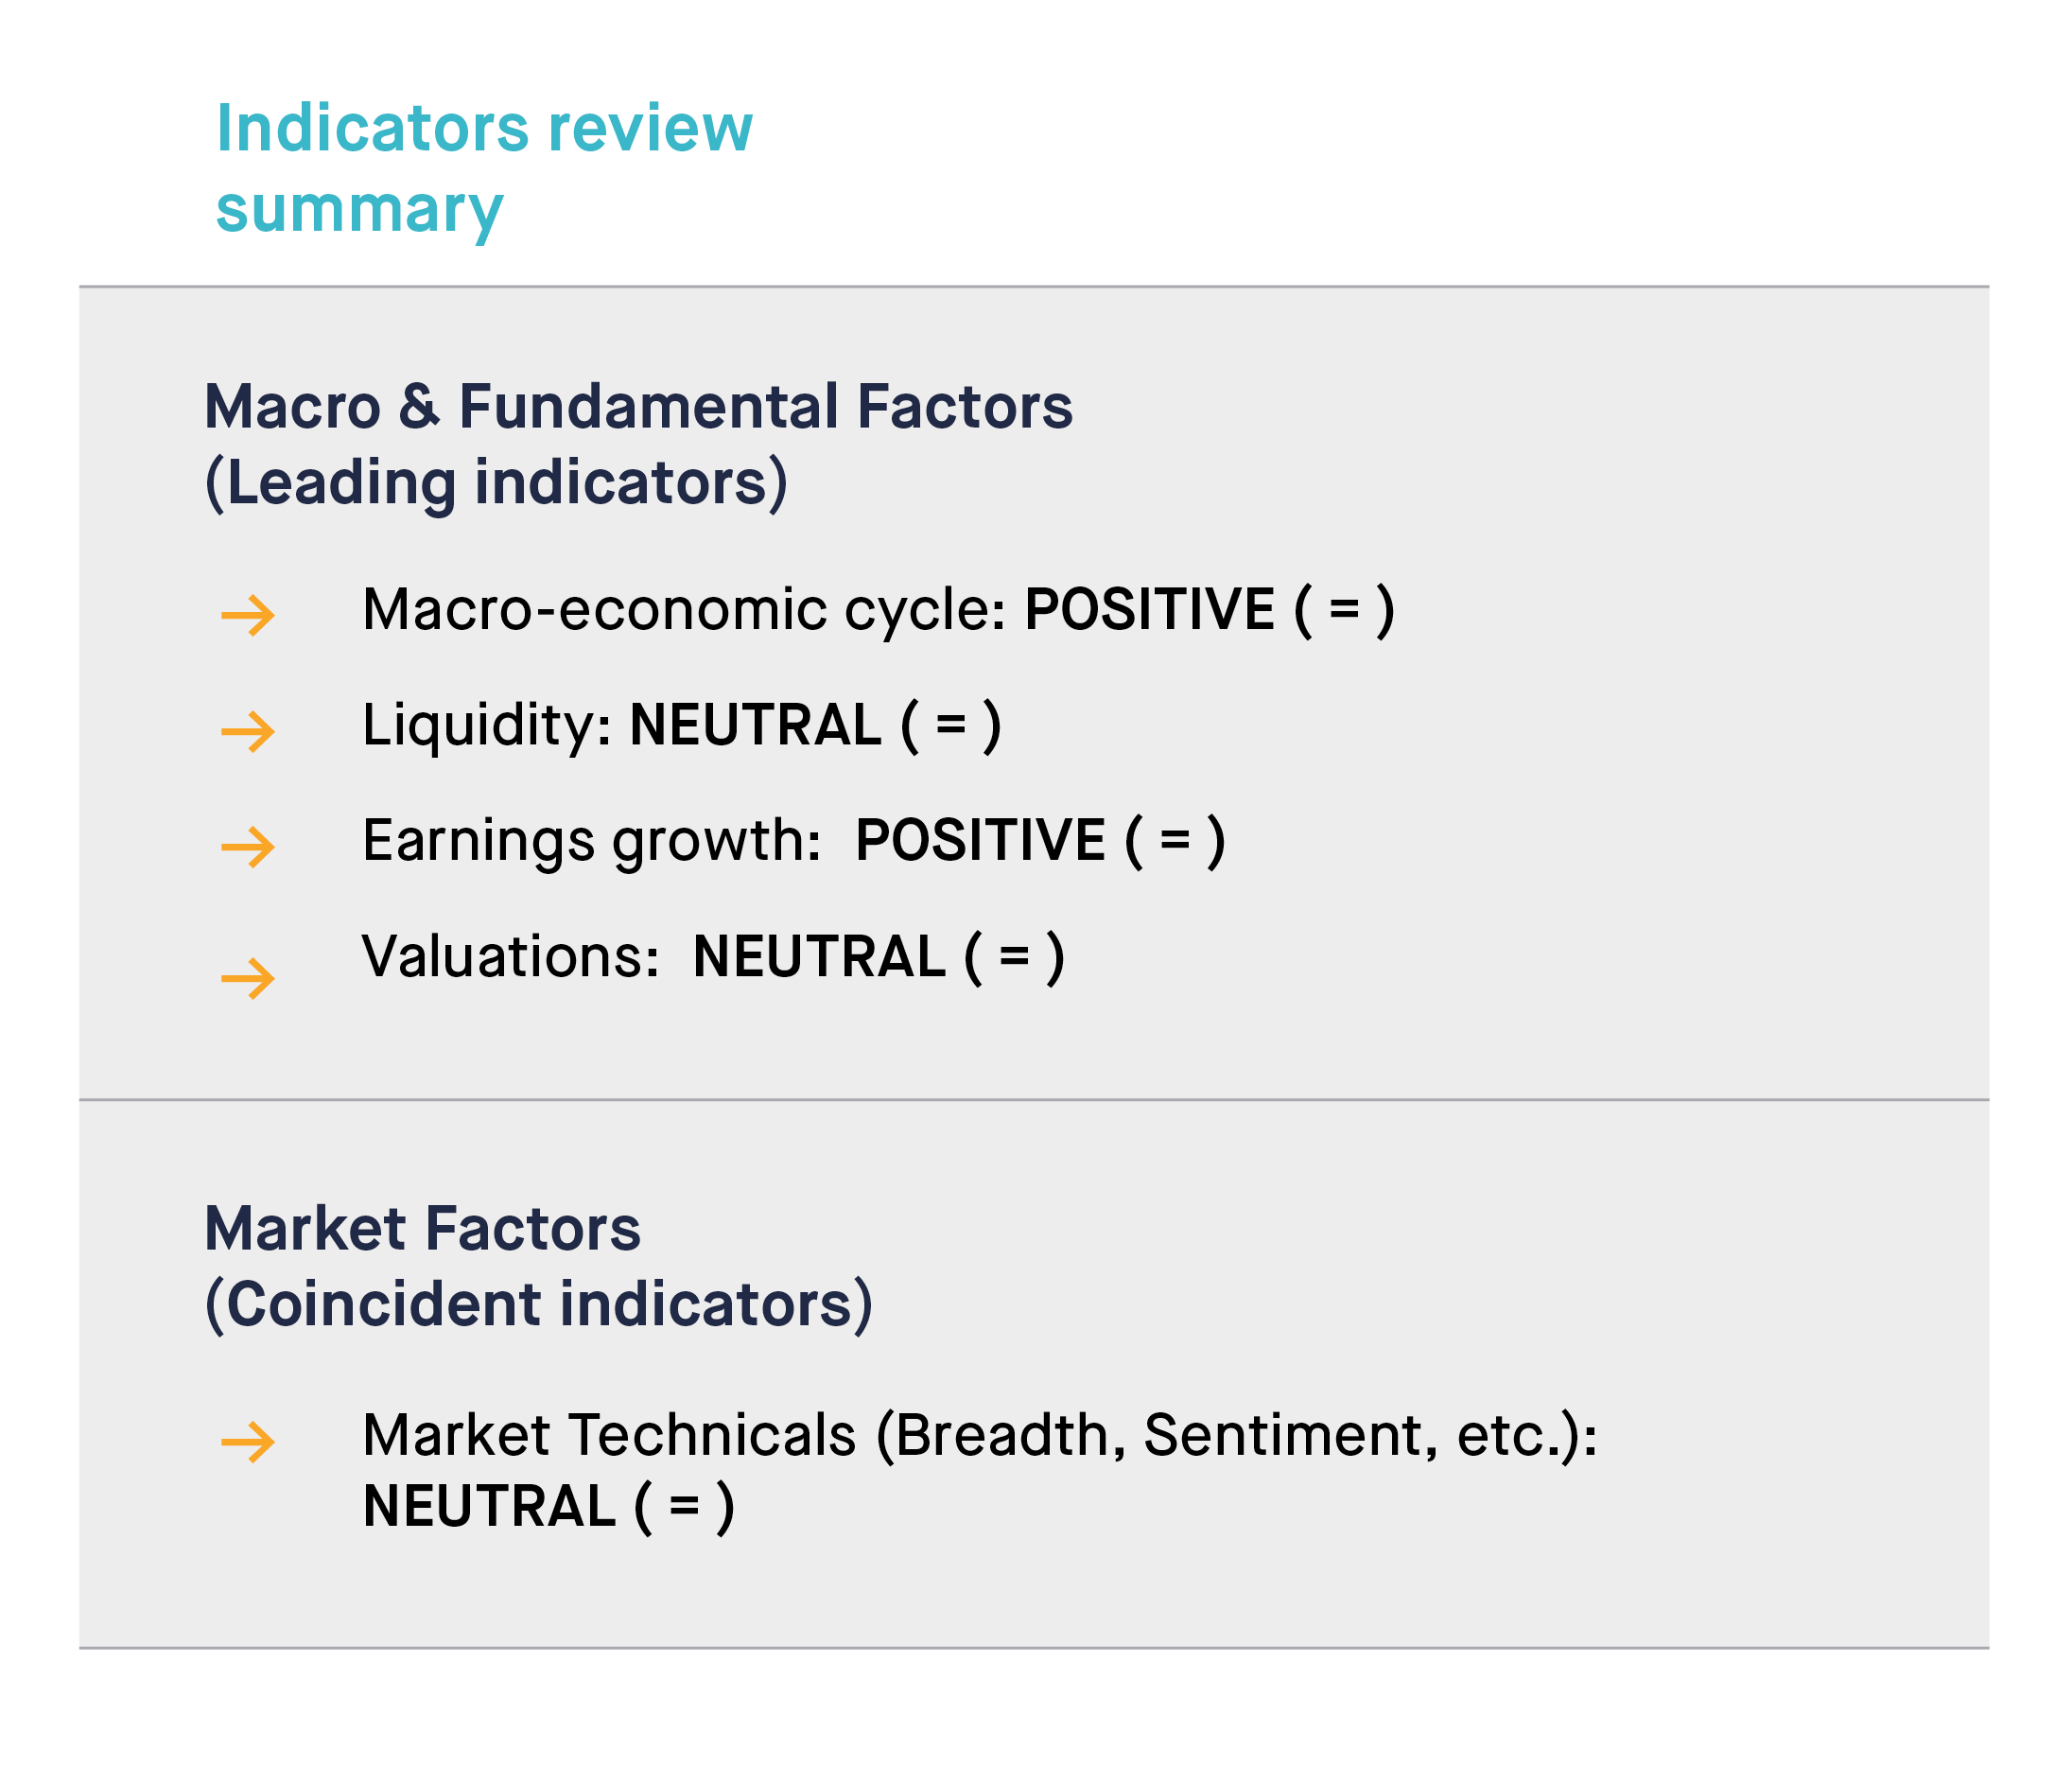
Global growth remains firmly positive even if the «Covid recovery effect» gradually fades away. The expansion in manufacturing and service sectors is broad-based, even if the momentum is softer compared to H1 2021. A positive development over the last few weeks stems from the fact that economic surprises are no longer deteriorating and are even turning positive in the US and the UK (see chart below). On the more worrying side, China growth has slowed down in 2021 on the back of the normalization in credit conditions and supply constraints. In the near-term, we do not see any appetite on behalf of Chinese authorities to accelerate the credit impulse. As such, weak growth momentum is likely to persist in the months ahead – at least until March 2022. The sub- par growth outlook in China is somewhat offset by strong growth momentum in the US. After a “soft patch” in the 3rd quarter, real GDP growth is re-accelerating meaningfully. While price and wage inflation are at a decade high, we believe that we have reached peak bottleneck and this should soon lead to peak inflation. Indeed, our view remains that higher Developed Markets inflation in 2021 is mostly due to transitory factors. While inflation is likely to stay high in the medium-term, we expect it will progressively converge towards central banks’ target throughout 2022.